A founder is reviewing supplier payments at 22:00, approving a discount by WhatsApp and answering a key customer before the next morning. Revenue may be growing, but the enterprise still depends on one person remembering every commitment. That is the point at which a business growth consultant for SMEs can help turn owner-led activity into an institution.
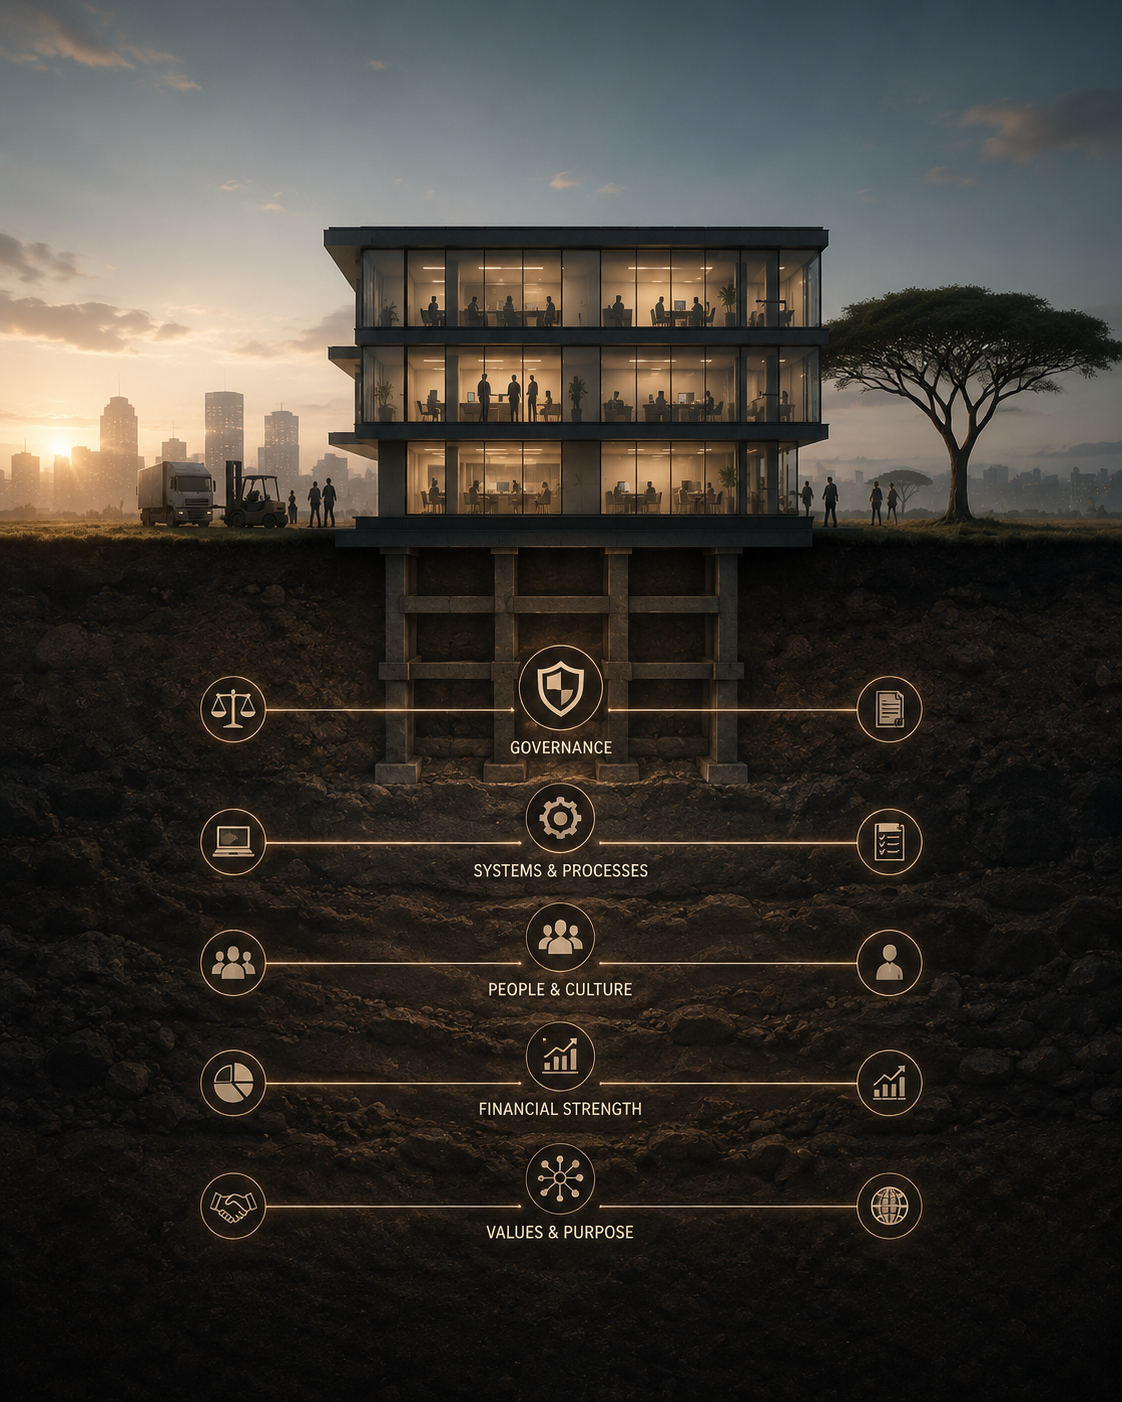
For South African enterprises, institutional growth means moving important decisions into documented governance, delegated authority, management reporting, standard operating procedures, cash-flow controls and an accountable leadership team. We help owners make that transition without losing the commercial judgement that built the business.
This is a South Africa-focused advisory article. The principles can inform African expansion, but tax, company law and transformation requirements change by jurisdiction.
When an owner-run business reaches its limit
Owner involvement is valuable in an early-stage enterprise. The problem begins when every payment, price exception, recruitment decision and customer complaint waits for the founder. Growth then increases pressure rather than enterprise value.
We usually see the strain in five places: delayed management accounts, inconsistent customer margins, slow debt collection, undocumented staff decisions and an owner who cannot take a week away from operations. None of these issues will appear on a Companies and Intellectual Property Commission, or CIPC, filing. Each can still weaken the company before a lender, investor or procurement panel reviews it.
The Company’s Act has applied since 1 May 2011. It requires directors to act in good faith, for a proper purpose, in the company’s best interests, and with appropriate care, skill and diligence. A business cannot meet that standard through informal conversations alone when its decisions affect payroll, tax, contracts and cash.
A practical test for institutional readiness
Ask a direct question: if the owner became unavailable for 30 days, who could approve a R150,000 purchase, release a customer order on credit or explain the cash position to a bank? If the answer is unclear, the business has a founder-dependency risk.
We do not advise a R3 million turnover business to build a board structure designed for a listed company. We advise it to document decision rights, set approval limits and produce a short monthly pack. The right system should match the enterprise’s size, risk and growth plan.
Take an illustrative Johannesburg distributor with annual revenue of R18 million and 14 staff. Its owner approved all supplier payments and gave sales staff verbal authority to offer discounts, which left finance unable to explain why gross margin moved from one month to the next. The company allocated R45,000 to map its approval process, introduce a discount matrix and prepare a monthly margin report. Within three months, the owner could identify which of its five largest accounts generated revenue but absorbed disproportionate delivery and credit costs. With hindsight, the business would have introduced those controls before opening a second warehouse.
What a business growth consultant for SMEs should build
Growth advisory should produce operating discipline, not a presentation that sits in a shared drive. We begin with the commercial decisions that already consume the owner’s time, then decide which must remain with the owner and which can move to a named manager.
1. Decision rights and delegated authority
A delegation framework identifies who may commit the enterprise to spending, credit, recruitment, contracts and pricing decisions. It should state the approval amount, the evidence required and the person accountable for checking it.
For example, a sales manager may approve a discount within an agreed margin floor, while any exception below that floor requires finance review and executive approval. This protects margin without forcing the owner to review every quote.
The common mistake is treating delegation as a loss of control. It creates clearer control when the owner can see who made a decision, under which limit and with what result. We recommend starting with the decisions that create the largest cash exposure: customer credit, supplier commitments and payroll changes.
2. A monthly institutional dashboard
A monthly dashboard gives management one version of commercial reality. It should cover the revenue pipeline, gross margin, customer concentration, working capital, debtors, cash runway, tax status, people metrics and delivery KPIs. This is advisory best practice rather than a statutory template.
The dashboard must answer questions, not merely report totals. If debtors rise from R1.2 million to R1.8 million, management needs an aged-debtors list, named account owners and a collection action for each material balance. If one customer represents 38% of revenue, the leadership team needs a retention plan and a view of the exposure.
We advise monthly reporting within a fixed number of working days after month-end, with the same definitions each month. A gross-margin figure loses value if operations include freight in one month and exclude it in the next.
3. Cash-flow controls that match growth
Revenue does not pay salaries until customers pay their invoices. An institutional SME tracks weekly cash in, cash out, overdue debt, committed supplier payments and the date at which available cash becomes constrained.
A rolling 13-week cash-flow forecast often gives a management team more useful control than an annual budget alone. It forces the team to connect customer collections, stock purchases, payroll and tax dates. The forecast should have a named owner, and management should compare actual cash movement against the prior forecast each week.
Take an illustrative Cape Town services firm with twelve staff and a monthly payroll of R600,000. It had R2.4 million in invoices issued, but R900,000 was older than 60 days, while the founder continued to approve new work for the same late-paying customers. The business spent R25,000 on a finance-process review and assigned collection responsibility to account leads, with weekly escalation for invoices over 30 days. Its first lesson was uncomfortable: it had treated invoicing as an administration task rather than a commercial control. It would now set credit terms and collection ownership before accepting a large project.
4. Leadership roles and operating routines
An accountable leadership team needs more than job titles. Each executive or manager should own defined outcomes, a small set of measures and a regular decision forum.
A weekly operating meeting can cover delivery, sales, cash and people risks. A monthly management meeting can review the dashboard, approve material decisions and record actions with owners and due dates. Minutes matter because they show what management considered and how it acted.
We also use standard operating procedures where mistakes recur: onboarding a customer, issuing a quote, approving a supplier, hiring staff and closing a month. Do not document every minor task first. Start with the processes that affect cash, compliance, customer experience or margin.
Build compliance into the growth plan
Compliance becomes more demanding as an enterprise grows. Treating it as a year-end task creates avoidable risk and distracts leadership when they should focus on customers and delivery.
CIPC obligations and corporate governance
CIPC is the core corporate-compliance portal for South African companies and close corporations. Companies and close corporations must submit annual returns, beneficial-ownership declarations and the applicable beneficial-interest or security register within 30 business days after their anniversary date.
CIPC introduced the beneficial-ownership filing rule on 24 May 2023. Filing an annual return while assuming beneficial-ownership information can wait is a frequent error because CIPC links these obligations. Late filing can lead to penalties, enforcement action and deregistration.
CIPC bulk-deregistered entities during December 2024, with final deregistration’s beginning in February 2025, for failures involving annual returns, beneficial ownership and financial statements. That history makes a compliance calendar a governance requirement, not an administrative preference.
We recommend that the company secretary function, finance lead or appointed advisory partner owns a calendar that records the anniversary date, 30-business-day deadline, supporting documents and final filing confirmation. The director still retains responsibility for oversight.
SARS thresholds that change the finance function
As of September 2026, SARS requires compulsory VAT registration once annual taxable supplies exceed R2.3 million. Voluntary VAT registration begins above R120,000. SARS administers VAT registrations through eFiling, including form RAV01.
These thresholds changed on 1 April 2026, when compulsory registration increased from R1 million and voluntary registration increased from R50,000. A business approaching R2.3 million should prepare its invoices, pricing, accounting records and finance capability before it crosses the threshold, because late or backdated registration can create penalties and interest.
Do not treat VAT registration as an accounting event only. It changes how the enterprise prices work, captures supporting documents and communicates with customers who expect VAT-compliant invoices.
Standard corporate income tax is 27% for years ending from 1 April 2026 to 31 March 2027. A qualifying Small Business Corporation, with only natural persons as shareholders or members and gross income not above R20 million, uses progressive rates: 0% up to R99,000 taxable income, 7% to R365,000, 21% to R550,000, then 27%.
This is an area for tax advisory, not assumption. Eligibility depends on the entity’s facts, so directors should review ownership, income and tax status before relying on Small Business Corporation treatment. Statutory tax treatment should be reviewed by a qualified M&J team member before action.
Choose Turnover Tax with a model, not a preference
Turnover Tax may suit qualifying micro-businesses with annual turnover of R2.3 million or less. For the 2026/27 cycle, rates begin at 0% on the first R600,000 and rise to 3% above R1.4 million.
We would not select Turnover Tax solely because it appears simpler. Model ordinary income tax, VAT, expected profitability, input VAT and the next 12 to 24 months of growth before deciding. A low-margin trader with meaningful input VAT may reach a different conclusion from a professional-services business with limited input costs.
Use transformation and procurement positioning carefully
B-BBEE positioning can influence access to corporate procurement opportunities and transformation planning. Under the general-code framework, an Exempted Micro-Enterprise, or EME, has annual turnover up to R10 million, while a Qualifying Small Enterprise, or QSE, falls between R10 million and R50 million.
Check the applicable sector code before claiming a status or planning a tender strategy. A generic classification can be the wrong basis for an enterprise operating under a sector-specific code.
The practical point is timing. If a growing business expects to cross R10 million, management should understand the reporting and procurement implications before a customer asks for evidence. This work belongs in the growth plan alongside company registration records, finance controls and human capital planning.
A 90-day institutionalisation programme
We structure growth advisory around decisions that produce visible control early. The first 90 days should leave the owner with clearer information, named accountability and a compliance calendar.
Days 1 to 30: Diagnose the pressure points
Map the decisions that still wait for the founder. Review the last three months of management information, aged debtors, major contracts, company registration records, CIPC standing, SARS status and customer concentration.
We also identify the few processes where a mistake carries the highest cost. For many SMEs, those are credit approval, quoting, procurement and payroll.
Days 31 to 60: Design the operating system
Set approval limits, define management roles and agree the first dashboard. Establish the weekly cash routine and monthly management meeting, then record the actions that each leader owns.
Keep the first version usable. A five-page management pack that leaders read and discuss is better than a 30-page report that arrives too late to influence a decision.
Days 61 to 90: Embed and test accountability
Run the first monthly review using live figures. Test whether a manager can make a decision within the delegated limit, whether finance can explain cash runway and whether the compliance owner can produce required filing evidence.
Then refine the system based on what did not work. Institutionalisation is a management habit, not a one-time compliance project.
Frequently Asked Questions
What does a business growth consultant for SMEs do?
We assess the constraints that keep an owner central to every decision, then help build governance, financial controls, leadership accountability and operating routines. The work should produce practical tools such as delegated authority limits, a cash-flow forecast, a management dashboard and a compliance calendar.
When should a South African SME register for VAT?
As of September 2026, SARS requires VAT registration when annual taxable supplies exceed R2.3 million, while voluntary registration starts above R120,000. Businesses nearing either threshold should review invoices, pricing and accounting processes before applying through SARS eFiling using RAV01.
What must companies file with CIPC each year?
Companies and close corporations must submit annual returns, beneficial-ownership declarations and the applicable beneficial-interest or security register within 30 business days after their anniversary date. CIPC has linked these obligations, so management should not postpone beneficial-ownership information after filing an annual return.
Should a growing SME use Turnover Tax?
It may suit a qualifying micro-business with turnover of R2.3 million or less, but the decision requires a comparison against ordinary income tax and VAT. If the business expects rapid growth, has meaningful input VAT or operates on thin margins, model the options before electing.
A business can keep its founder’s commercial instinct while building an enterprise that customers, staff, investors and regulators can trust. Speak With Our Team to discuss a growth advisory programme for your South African SME.